The second-life EV battery business is the rare case where the hype phrase describes a real business with a limited market, and the distinction between the two halves of that sentence is the whole subject. A traction battery that no longer meets a vehicle’s performance requirements retains a large fraction of its capacity, and that retained capacity is genuinely useful in stationary applications whose duty is gentler than a car’s. That is real. The question is how much of the spent stream it absorbs, and the honest answer is a fraction that is significant and bounded, and the boundary is set by the economics of testing, not by the chemistry.
The mechanism is worth stating because the business’s reality depends on it. A battery retired from vehicle service has accumulated capacity loss, thermal history and degradation that vary cell by cell, and the second-life business’s cost is the measurement of that condition, because every module that goes into a stationary system has to be characterised enough for the duty it will serve. The testing and repackaging cost is the trade’s margin problem, and it is why the market that has developed is real at the scale where testing is cheap, in the applications where the duty is undemanding enough that the modules’ variance is tolerable, and why the hype version, in which the spent stream is simply re-sold, ignores the characterisation step that decides the price. The business is real wherever the testing is economic, and it is hype wherever the assumption is that it is not needed.
The amount of material the business sits inside is worth knowing because it frames the scale. The Global E-waste Monitor’s composition data for the world’s 2022 e-waste counts about 34 million kilograms of cobalt and traces lithium in the waste stream alongside it, and the electric vehicle fleet’s own batteries add a spent stream measured outside the e-waste figures, in a category the charging and transport standards treat separately from waste until they are discarded. The Monitor’s documented rate for the world was 22.3 per cent in 2022 with a projection of 20 per cent by 2030, and the collection system the second-life business relies on is the same collection system the material figures rely on. The market and the collection rate are connected, and the business’s serious participants are the ones who know it.
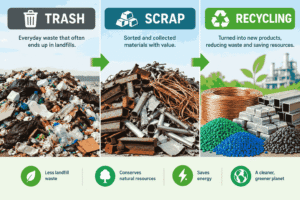
The comparative that settles the question is the recycling route’s economics, and it is a straightforward comparison. A spent battery’s second-life value has to be compared with its material-recovery value, and the transition’s critical-materials prices have made the recovery route competitive with repurposing for modules that are borderline, which is why the second-life market has developed in the applications where reuse is clearly cheaper than shredding. Where the comparison is close, the market sorts by price and not by preference, and the recycled-content provisions in the European battery rules and the American domestic-content credits change the comparison on the material-recovery side, which is the direction the policy has chosen. The business is real where the economics are unambiguous, and it becomes hype when the policy’s demand for recycled content makes the alternative worth more.
Why now is the fleet’s retirement curve and the rule-writing arriving together, and the second-life market’s shape will be decided inside the next decade. The world’s generation has risen five times faster than documented recycling since 2010, the battery rules in the major markets write recycled content and collection targets on schedules that arrive across the 2030s, and retired electric vehicle batteries are becoming a measurable stream in exactly the period the rules create their demand for the material. The second-life market’s serious participants are building testing capacity and the recycling route’s participants are building recovery capacity, and the two compete for the same modules, which is a market rather than a mission.
What should happen is the honest treatment of second life as a sorting decision rather than a destination, because that is what the market has already decided it is. A retired battery stream’s testing, grading and allocation between reuse and material recovery is the trade the sector runs, and the policy’s useful role is in the standards that make the characterisation cheap, which is what moves the boundary between the two destinations rather than the preferences of either side’s advocates. Every other framing produces the hype version of the question, and the market has been answering it in price terms since the first retirements.
For traders, the second-life business is a grade question, because the market’s material is a tested module rather than a used battery, and the tested modules are what the stationary integrators buy. The Global E-waste Monitor 2024 holds the material and collection figures above, and platforms such as scrap.trade carry the documented trade in the tested and graded material the sector’s real business consists of. The International Energy Agency holds the deployment data the second-life market’s scale depends on, and the sector’s serious participants are its most careful readers.
Second-life EV batteries are a real business with a bounded market, and the boundary moves with the testing cost and the recovery price, which are both moving. The honest answer to the title is that real is what the testing economics permit, and the hype is what the testing economics have not yet reached. The market has been sorting this question by price since the first retired modules were characterised, and the sorting will continue, which is the boring answer to a question that was designed to have an exciting one.